
The No-Debt Christmas: A Holiday Spending Plan That Works
A no-debt Christmas or a debt-free holiday comes down to deciding what you'll spend before December decides for you. Set a total holiday number, split it across every category you'll actually spend on, and move money toward it weekly starting now.
Most holiday debt isn't caused by one big purchase. It builds from a dozen small ones that nobody planned for: the extra gift for a coworker, the host gift, the second round of wrapping paper, the takeout on the night you were too tired to cook after shopping.
With a few weeks left before the season gets loud, you still have time to build a holiday spending plan that works. Here's how we'd approach it.
How Much Should a No-Debt Christmas Cost?
Pick your number first. Not the number you spent last year, and not the number a store flyer suggests. The number your household can move out of its income between now and late December without touching rent, groceries, or your loan payments.
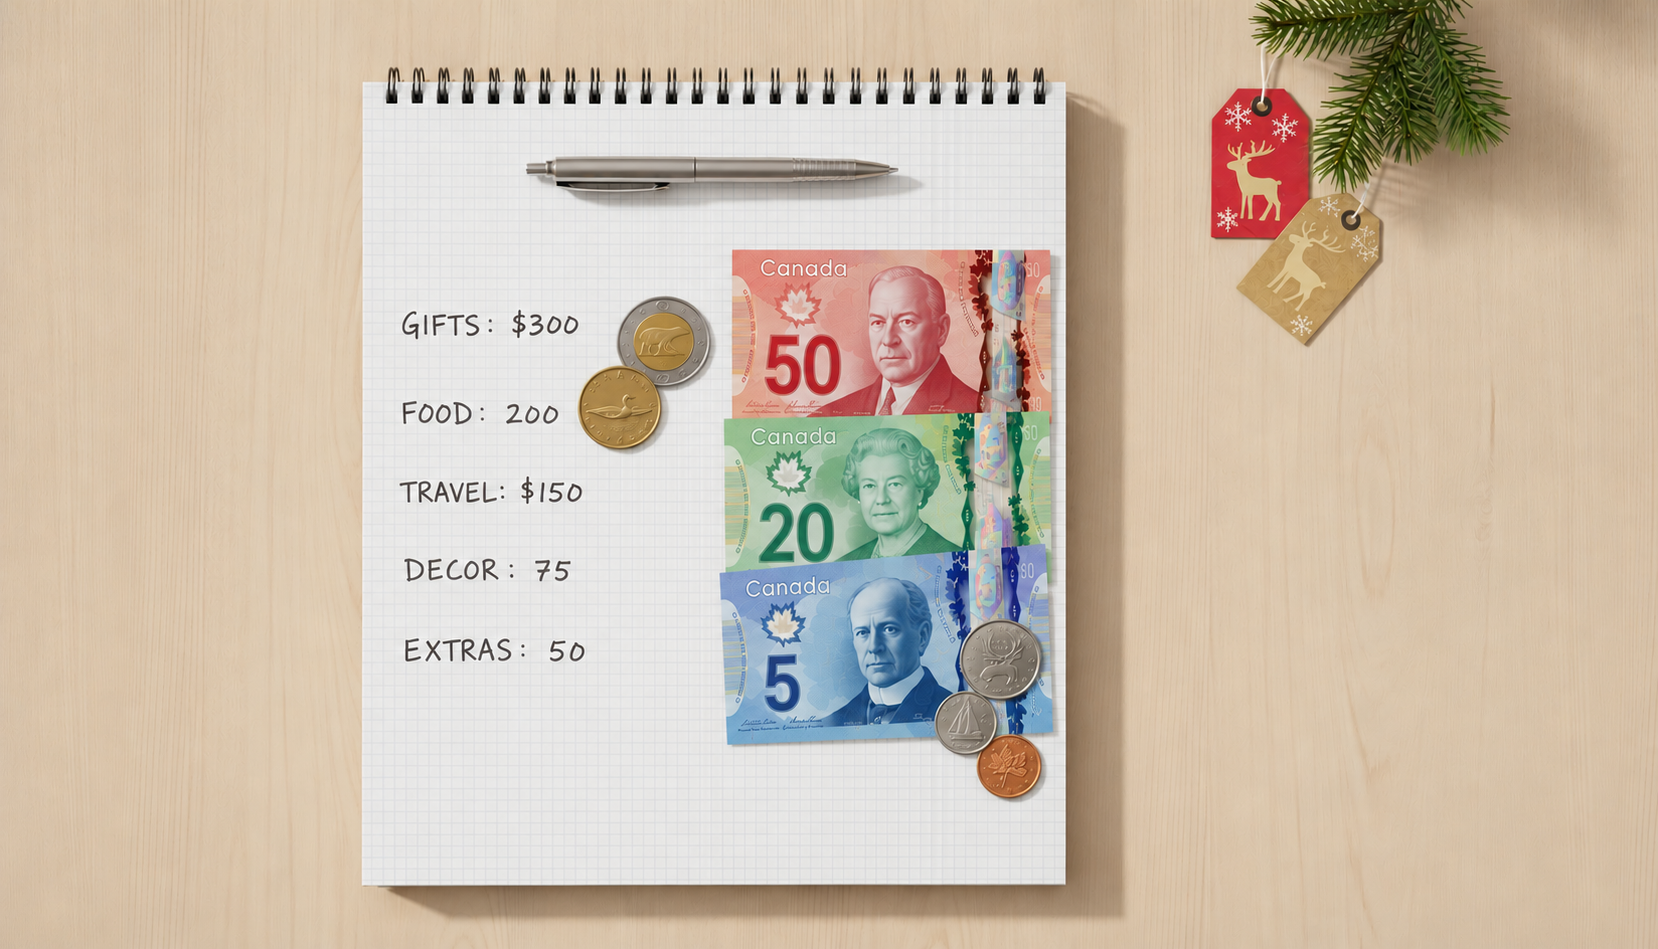
Then break that number into categories, because a single lump sum is almost impossible to track. A realistic list looks like this:
- Gifts: One line per person, with a dollar amount beside each name.
- Food and hosting: The big dinner, plus the smaller get-togethers that sneak up on you.
- Travel: Fuel, flights, pet sitting, or accommodation.
- Decor and wrapping: Usually underestimated, almost never zero.
- Extras: Tips, teacher gifts, donations, holiday outfits.
Write the names and numbers down somewhere you'll see them. A list on the fridge beats a plan you're holding in your head, and it gives everyone in the household the same expectations before anyone starts shopping.
If you've never set a monthly number before, our beginner's guide to creating a monthly budget in Canada walks through the same process for the rest of the year.
How to Save Money Heading Into the Holidays
Saving is less about cutting back hard and more about redirecting money you're already spending. Starting in mid-October or even November, still gives you time to set aside a little from each paycheque before the bulk of your holiday spending hits.
Find The Money You're Already Losing
Start with the recurring charges. Streaming services you stopped watching, app subscriptions renewing annually, the gym membership you've used twice since summer.
Cancelling some of these frees up cash every single month, not once. Our post on how to track spending and stop wasting money on monthly subscriptions covers how to find them quickly.
Then try these:
- Open a separate holiday account. Keeping the money out of your main chequing account makes it harder to spend by accident.
- Automate a weekly transfer. Smaller amounts moved often feel easier than one large transfer in December.
- Shop the list, not the sale. A discount on something nobody asked for is still money gone.
- Set a gift exchange with the adults. One name each instead of gifts for everyone cuts the biggest category fast.
- Start now on the big-ticket items. Spreading purchases across three paycheques avoids one brutal credit card statement.
What If Your Holiday Spending Plan Still Comes Up Short?
Sometimes the gap isn't caused by poor planning. A furnace quits in November. The car needs work before a drive home for the holidays. The season arrives on top of expenses you were already carrying.
If that's where you are, the goal shifts from avoiding every dollar of borrowing to borrowing in a structured way with a clear end date. A fixed term with set payments is easier to plan around than a revolving balance that follows you into spring. That's the thinking behind installment loans and credit rebuilding, and behind debt consolidation loans for people juggling several balances at once.
Unexpected emergencies fall into the same category. A vehicle repair loan handles the problem on a schedule you can see, instead of on a credit card you'll be paying down in July.
Why Choose JP Financial?
We've been working with Canadians since 2003, and we've heard every version of the holiday money conversation. Our approach is approval focused rather than credit obsessed. We look at your full picture, not only a number on a credit report, which is why we work with applicants who have good or bad credit.
There are no upfront fees with us, and we move quickly, because a funding decision that takes weeks doesn't help anybody in December. Many of our customers upload their required documents the same day they’re pre-approved and receive their funds later that day, once final approval is complete. You'll also deal with real people throughout the process.
We offer personal loans of up to $5,000 nationwide, excluding Manitoba and Quebec. If you're wondering who we are before you apply, find your answer in is JP Financial a legitimate non-bank lender in Canada.
FAQs
When should I start saving for Christmas?
Ideally in January, but the second-best time is right now. Starting in late October still gives you several paycheques before the heaviest spending weeks, which is enough to cover a meaningful share of a planned holiday budget. The earlier you start, the smaller each weekly transfer needs to be. Even four weeks of automated saving reduces what lands on a credit card.
How do I set a realistic holiday budget?
Work backward from your income rather than forward from your wish list. Decide what you can move aside each week without affecting rent, groceries, utilities, or existing loan payments, multiply it by the weeks remaining, and that total is your holiday budget. Then split it across gifts, food, travel, and decor, assigning a name and dollar figure to each line.
Can I get a personal loan in Canada with bad credit?
Yes. We work with Canadians across the credit spectrum and focus on approval rather than a score alone. Our guide on how to qualify for a personal loan with bad credit in Canada explains what helps your application and what lenders actually look at beyond your credit score covers the other factors in the decision.
What happens when a lender runs a credit check?
A lender reviews information from your credit file as part of reviewing your application, which can include your payment history and existing accounts. We break down the specifics of what information lenders see during a credit check in Canada. Knowing what's on your file before you apply removes a lot of the guesswork.
Conclusion
A no-debt Christmas or a debt-free holiday isn't about spending less than everyone around you. It's about knowing your number, splitting it into categories, and moving money toward it on a schedule. The plan does the hard part so December doesn't have to.
If the gap is bigger than the weeks remaining, talk to us. Start a personal loan application or browse our lending hub for straight answers, with no up-front fees and a real person on the other end.